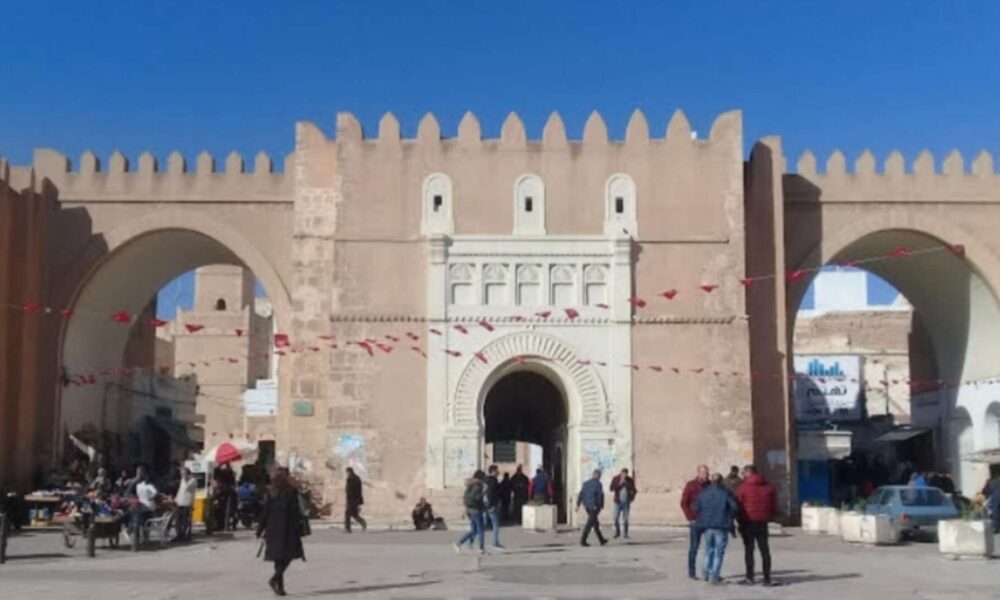
What if Tunisia did not suffer from a shortage of resources, but from a misdirection of those it already possesses? Tax receipts, bank savings, diaspora remittances, exceptional sunshine: the country has considerable reservoirs, of which water does not always reach the fields where it would be useful.
The context makes this question urgent. In 2025, growth reached 2.5%, up from 1.5% a year earlier, driven by agriculture and tourism. But investment remains stuck at 16% of GDP, far from the 25% generally deemed necessary for a sustainable takeoff, and growth is expected to fall back to 2.1% in 2026 before rising to 2.8% in 2027.
This is the diagnosis laid out by the 2026 Country Report on Tunisia by the African Development Bank, published within the framework of the Economic Outlook for Africa 2026. Its starting point is unequivocal: catching up with structural transformation would cost $4.5 billion per year by 2030, i.e., 8.5% of GDP, with a financing gap of $3.25 billion.
A State That Pays Its Expenses First
The first bottleneck lies in the public accounts. The deficit fell to 5.2% of GDP in 2025, down from 6.4% in 2024, but debt remains at 82.1% of GDP. Public salaries, subsidies and debt service now absorb two-thirds of the state’s expenditures, compared with 41% in 2011. There is little room left for roads, schools or hospitals.
In the absence of affordable external financing, the Treasury turns to local banks. At the end of 2025, net claims on the central administration represented nearly 35% of the domestic assets of deposit-taking institutions. They rose by more than 20% over the year, compared with about 3% for loans to the economy. In other words, Tunisian savings finance the state before financing the entrepreneur.
The Fiscal Paradox